Updated: November 2026. Added how a cross-border payment works today, with 2025 cost and speed data from the World Bank and the FSB. Regulatory sections cover MiCA, the GENIUS Act, and the EU Transfer of Funds Regulation.
A cross-border payment is a transfer where the payer and the recipient sit in different countries, and usually in different currencies. Through banks, it still passes through a chain of correspondent accounts, and the average cost of sending a USD 200 remittance was 6.36% in Q3 2025. Stablecoin payment rails replace that chain with one onchain transfer that settles in seconds, 24/7.
In 2026 the regulatory perimeter is no longer theoretical: MiCA is in full effect across the EU, the GENIUS Act is law in the US, and the EU Transfer of Funds Regulation requires originator data on every crypto transfer. If you're a developer embedding stablecoin rails inside an app (fintech, neobank, remittance, marketplace, agentic spend), those rules apply to you.
This guide covers how a cross-border payment works today, what it costs, where stablecoin rails fit, and the compliance map for builders. If you're building a remittance product specifically, the stablecoin remittances infrastructure guide covers the build. To route payments across several providers, see payment orchestration for stablecoin payments.
How a cross-border payment works today
A bank cross-border payment has two parts: a message and a settlement. The message travels over Swift, which carries the payment instruction between banks. The money moves through correspondent banking: banks hold accounts with each other in the currencies they need, and the payment hops along those accounts until it reaches the recipient's bank.
Each hop adds cost and delay:
- Fees at every bank in the chain. The sending bank, any intermediary, and the receiving bank can each deduct a fee. The FSB's survey of payment providers found receiver-side costs of 0.1% to 1.3% of the amount sent on average, on top of what the sender pays.
- FX margin. Currency conversion is the largest component of cost for retail cross-border payments, according to the same FSB report.
- Cut-off times and banking hours. Most RTGS systems that settle the domestic legs run on weekdays only, so a payment sent on Friday evening can wait until Monday.
- The beneficiary leg. The receiving bank's processing, from the Swift instruction arriving to the money landing in the customer's account, has been the slowest part of a cross-border payment, according to the FSB.
The correspondent network is also thinning. The BIS counted about 22% fewer active correspondent banks between 2011 and 2019, while payment volumes kept growing. Fewer banks carrying more traffic means some corridors have only one or two expensive routes.
Cross-border payment cost and speed in 2025
The G20 has a roadmap to make cross-border payments faster and cheaper, with most targets due at the end of 2027. The FSB's October 2025 progress report says satisfactory improvement at the global level is unlikely on that timetable. The latest figures:
| Measure | Value | Source |
|---|---|---|
| Average cost of sending a USD 200 remittance | 6.36% (Q3 2025) | World Bank RPW, Issue 54 |
| Same, through a bank | 14.99% (Q3 2025) | World Bank RPW, Issue 54 |
| Same, through a digital service | 4.59% (Q3 2025) | World Bank RPW, Issue 54 |
| G20 remittance cost goal | 3% | World Bank RPW, Issue 54 |
| Average cost of a retail person-to-person cross-border payment | About 2.5% (2025) | FSB, 2025 progress report |
| Retail cross-border payment services settling within one hour | 35.4% (2025) | FSB, 2025 progress report |
| Retail cross-border payment services settling within one business day | 67.3% (2025) | FSB, 2025 progress report |
| Wholesale payments (USD 100,000 and above) credited within one hour | More than 50% (2025) | FSB, 2025 progress report |
Two things stand out. More than half of large bank-to-bank payments arrive within the hour, so the friction sits in retail and remittance corridors. And costs have barely moved: the FSB calls average global costs "sticky", with little change since it first measured them in 2023.
How a stablecoin cross-border payment works
A stablecoin cross-border payment replaces the correspondent chain with three steps:
- On-ramp. The sender converts local currency to a stablecoin such as USDC, or already holds one. See the crypto onramp guide.
- Transfer. The stablecoin moves from the sender's wallet to the recipient's wallet in one onchain transaction. It settles in seconds to minutes, at any hour, and the network fee is a fraction of a cent on low-cost chains. Solana's base fee is 5,000 lamports (0.000005 SOL) per signature. Sending a token to a recipient for the first time can also require a one-off account creation deposit on Solana.
- Off-ramp. The recipient keeps the stablecoin, spends it, or converts it to local currency through a local provider, which pays out over a domestic rail such as Pix, SEPA Instant, or FedNow.
| Bank cross-border payment | Stablecoin cross-border payment | |
|---|---|---|
| Instruction and settlement | Swift message, then correspondent accounts | One onchain transfer does both |
| Intermediaries | Sending, intermediary, and receiving banks | Wallet providers and the on-ramp and off-ramp at each end |
| Hours | Banking hours and cut-off times on each leg | 24/7, including weekends |
| Where the cost sits | Fees at each bank plus FX margin | On-ramp and off-ramp spreads; network fee is negligible |
| Visibility | Status depends on each bank in the chain | The transfer is public onchain and final once confirmed |
| Compliance | Each bank screens the payment | Your app owns KYC, sanctions screening, and the Travel Rule where it is a custodial point |
The network fee is not the number to compare. A stablecoin payment is cheaper than a bank wire only if the ramps at both ends cost less than the bank route in that corridor. Where the recipient keeps the stablecoin, for example a contractor paid in USDC, the off-ramp drops out and the saving is largest.
SWIFT alternatives for cross-border payments
SWIFT is a messaging network, not a settlement system. It carries payment instructions between banks, and the money moves through correspondent accounts behind it. Swift reports that 90% of cross-border payments on its network reach the destination bank within an hour. The slow and expensive parts sit outside that hop: the beneficiary bank's processing, compliance checks, cut-off times, and the fees and FX markups each bank in the chain adds.
Each alternative replaces a different part of that chain:
| Alternative | What it replaces | Where it works | Trade-off |
|---|---|---|---|
| Domestic instant rails (SEPA Instant, FedNow, Pix) | The local legs of a payment | Inside one currency area | Not cross-border on its own, so you still need a cross-currency leg |
| Providers with local accounts in each country | Correspondent banking | The corridors the provider covers | You depend on that provider's licenses and corridor list |
| CIPS | SWIFT clearing for renminbi | Cross-border renminbi payments | Renminbi only |
| Stablecoins | Messaging, correspondent hops, and settlement | Anywhere a wallet can receive | The recipient needs an off-ramp to local currency, and the compliance work moves to you |
The domestic rails are now fast everywhere that matters for payouts. Since 9 October 2025, payment providers in the euro area must let customers send euro instant payments that arrive within seconds, at any hour. The Federal Reserve's FedNow Service has run 24x7x365 since 20 July 2023, and Brazil's Pix settles transfers in a few seconds every day of the year. CIPS is China's system for clearing and settling cross-border renminbi payments.
None of these crosses a currency border by itself. That is the gap stablecoins fill: one dollar-denominated asset that settles the same way in every corridor, which a local rail then turns into local currency at each end.
When stablecoins are the better SWIFT alternative
- The recipient can hold or spend the stablecoin, for example a contractor with a wallet, or a business that pays its own suppliers in USDC.
- Payments run outside banking hours, or you can't wait for a cut-off time on either side.
- You pay many recipients across corridors that no single provider covers. One stablecoin payout flow replaces a contract per corridor. See global payouts.
Stick with a bank or local-account provider when the recipient needs local currency in a bank account, the corridor already has a cheap provider, and you don't want to own the off-ramp and compliance steps. Getting funds into a wallet in the first place is a separate problem: see the crypto onramp guide.
Cost comparison beyond cross-border payments

For cross-border flows, compare the figures above: 6.36% on average for a USD 200 remittance and about 2.5% for a retail person-to-person payment, against a network fee of a fraction of a cent plus your on-ramp and off-ramp spreads. The ramps decide whether the stablecoin route is cheaper in a given corridor, so price them per corridor before you commit.
Businesses stand to gain the most. High fees from credit cards and processors eat into margins, 1.6–2.9% per transaction. Switching to stablecoins could improve profitability. For example:
- Walmart (2024 revenue: $648 billion) pays around $10 billion in card fees annually. Cutting to 0.1% could boost profits by over 60%.
- Chipotle (2024 revenue: $9.8 billion) loses $148 million to fees; stablecoins could increase profits by 12%.
- Kroger (low-margin grocer) might double its net income, as fees often exceed its razor-thin 2% margins.
Payment processors are adopting stablecoins too. Stripe now charges 1.5% for stablecoin payments, a 30% discount on card fees, and acquired Bridge.xyz for $1 billion. As processors like Stripe, Block, Fiserv, and Toast adopt stablecoins, fees will compress further, driving competition and accessibility.
Stripe vs. the builder path. Stripe charges 1.5% on stablecoin checkout, competitive against the 2.9% card-fee baseline, and after the Bridge.xyz acquisition (~$1.1B, Oct 2024) it doubled down on stablecoin acceptance for merchants. That works if you want acceptance and nothing else. It's the wrong fit if the wallet IS your product: fintech, neobank, remittance app, marketplace with stablecoin balances. For those, you assemble the rails yourself: a smart-account wallet on ERC-4337, KYC hooks into your chosen vendor, sanctions screening on every transfer, and a policy engine you control. Openfort exposes those hooks. Stripe abstracts them away.
Speed and settlement
A bank cross-border payment waits on cut-off times, compliance checks, and the receiving bank's processing at each hop. The FSB found that only 35.4% of retail cross-border payment services settled within one hour in 2025. Stablecoin transfers settle in seconds to minutes at any hour, which shortens the cash cycle for anyone paying suppliers, contractors, or users abroad.
This real-time edge helps businesses in emerging markets, like a Mexican garment maker paying a Vietnamese supplier. A bank route can pass through several correspondent banks, each adding fees, FX margin, and delay. A stablecoin transfer goes straight from one wallet to the other, and each side converts to and from local currency through a local ramp.
Travel Rule and KYC Thresholds: What Triggers What for Stablecoin Payment Rails
The Financial Action Task Force (FATF) Travel Rule (Recommendation 16) requires that originator and beneficiary information accompany virtual-asset transfers above a jurisdiction-specific threshold — typically around USD/EUR 1,000. The EU went further: as of 30 December 2024, the Transfer of Funds Regulation ((EU) 2023/1113) requires Crypto-Asset Service Providers (CASPs) to transmit originator and beneficiary data on every crypto-asset transfer, no threshold. The US side has FinCEN's $3,000 recordkeeping rule for funds-transfer originators (31 CFR 1010.410), the $10,000 Currency Transaction Report (CTR) threshold, and case-by-case BSA application to crypto businesses. Singapore's MAS Notice PSN02 sets the Travel Rule threshold at SGD 1,500. Other jurisdictions vary.
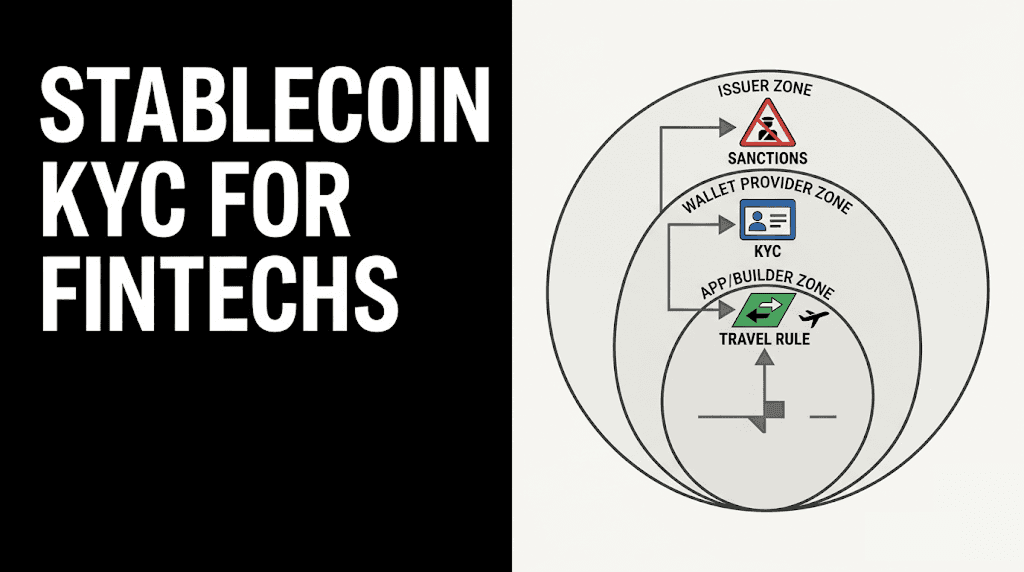
What this means for a developer embedding stablecoin payment rails: where the obligation lives depends on your wallet model. A self-custodial embedded wallet — keys held client-side, signed in the user's browser — typically does not make you a CASP/VASP in most jurisdictions. A backend wallet your service signs from IS a custodial point and DOES inherit obligations. In practice most production apps run both: an embedded wallet for the user (self-custodial) and a backend wallet for app-owned automation (custodial). Each has a different compliance posture, and your KYC + sanctions + Travel Rule integration has to be wired for each.

The primitives you need, destination allow-listing, per-user transfer limits, token allow-lists, programmable signing gates, are also the primitives a Travel Rule integration and a sanctions check need. Build them once at the wallet layer and your compliance vendor calls plug in. Openfort's smart-account wallets expose those primitives directly through the policy engine; you wire in your KYC vendor (Sumsub, Persona, Dotfile, your call), your sanctions list (OFAC SDN, EU consolidated, UK OFSI), and your audit log. The regulated entity in the flow, you, stays the policy enforcer.
See the stablecoin regulation and licensing guide for the jurisdiction-by-jurisdiction breakdown, and the stablecoin remittances infrastructure guide for the VASP / OFAC / FinCEN / MTL / CASP map applied to cross-border flows.
MiCA Article 75, the GENIUS Act, and What Changes for Builders
Two regulatory frameworks now define the perimeter for stablecoin payment rails.
MiCA (EU) has been in full effect since 30 December 2024 for crypto-asset service providers, with Title III (asset-referenced and e-money tokens) and Title V (CASP authorization) live across the bloc. Article 75 of MiCA governs the custody of crypto-assets on behalf of clients: segregation of client assets, books and records, the CASP's liability for loss. If you operate any custodial wallet inside the EU, Art. 75 applies to you: directly if you're authorized as a CASP, indirectly through your contracts with whichever CASP holds those assets.
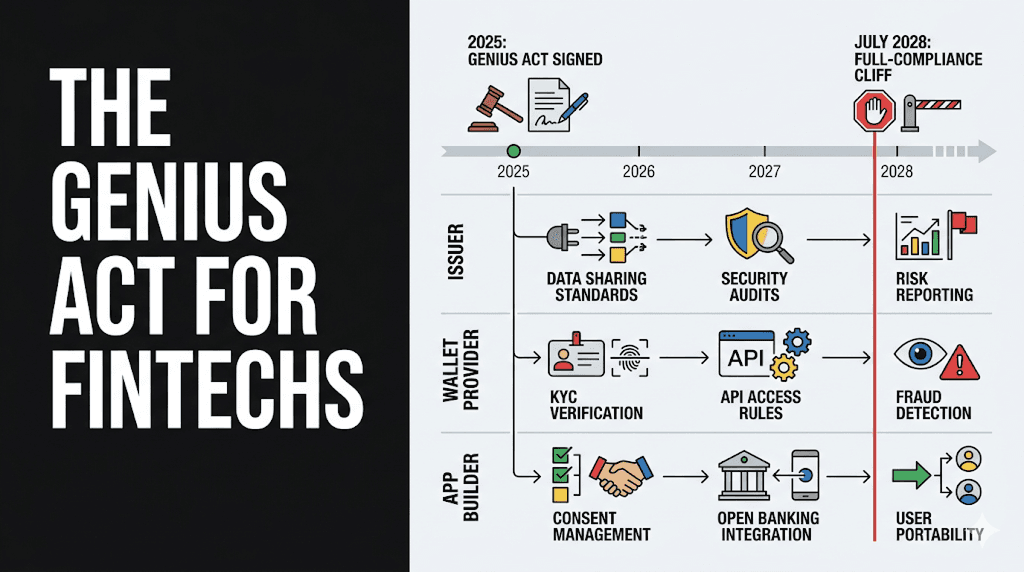
The GENIUS Act (US), signed into law in July 2025, establishes a federal framework for payment stablecoins. The rules that matter for builders: 1:1 reserve backing in cash or short-dated Treasuries, annual audits for issuers above $50B in issuance, OFAC sanctions screening on issuance and redemption, BSA/AML compliance, and a prohibition on algorithmic stablecoins. The Act's effective date for issuers lands in early 2027; the July 2028 cliff is the 3-year transition by which integrators (exchanges, custodians, wallet providers) must restrict activity to GENIUS-approved stablecoins.
A builder who is not issuing a stablecoin should still care, because issuer-side rules cascade through the distribution chain. Circle (USDC), Paxos (PYUSD, USD1), and the other GENIUS-compliant issuers will tighten their issuer-to-distributor terms as they ramp toward 2028. Apps that embed those tokens will see new requirements pass through: KYC at funding, sanctions checks on movements, recordkeeping on redemptions, and clearer terms around who carries liability when a wallet is compromised. The apps that already run a KYC + sanctions + policy stack at the wallet layer absorb these changes without disruption. The apps that don't have to replatform.
The compliance engineering minimum for stablecoin payment rails in 2026:
- KYC hook, integrated with a regulated KYC vendor; configured by user tier (limits, geographic gating).
- Sanctions screening on every outbound transfer (OFAC SDN at minimum; EU consolidated and UK OFSI if you serve those markets).
- Policy-engine rules per wallet: destination allow-lists, token allow-lists, per-user limits, method allow-lists.
- Audit log of every signed transaction tied to user identity and KYC tier.
Openfort's smart-account wallets ship with those hooks exposed. The regulated entity in the flow, your business, stays the policy enforcer, with the wallet primitives doing the load-bearing work. For the regulatory framework in depth, see Stablecoin Regulation and Licensing. For treasury-side wallet patterns, see Treasury Wallet.
Regulatory Landscape: Clarity Fuels Confidence
Regulation now gives builders clarity rather than blocking them. MiCA in the EU and the GENIUS Act in the US (covered in detail above) give builders the clarity they need to ship. Adjacent frameworks are catching up: the proposed CLARITY Act in the US, EU TFR for crypto transfers, MAS in Singapore, FCA in the UK, VARA in Dubai. For the full jurisdiction-by-jurisdiction map and which licenses attach to which roles in the stack, see the stablecoin regulation and licensing guide.
Accessibility and Financial Inclusion
Stablecoins democratize finance. Users need only a smartphone and wallet, no bank account. This matters for remittance corridors where banks are expensive: the World Bank measured banks at 14.99% on average for a USD 200 transfer in Q3 2025, against 4.59% for digital services. The onchain leg costs a fraction of a cent. The sender still pays for the cash-out at the receiving end.
Apps like Venmo, Apple Pay, PayPal, Cash App, Nubank, and Revolut now support stablecoins, easing onboarding. Issuers like Circle and Tether are sharing yields with partners, incentivizing businesses to convert users and keep funds onchain, much like credit card rewards, but more equitable.
Infrastructure and Operational Efficiency
By cutting intermediaries, stablecoins simplify operations. Fortune 500 firms report 71% cost reductions, 40% better working capital, and settlements in minutes. Emerging "stablecoin orchestration" tools integrate into back-office systems, handling payments, payroll, and subscriptions at near-zero cost without disrupting workflows.
Permissionless composability lets developers build atop stablecoins, creating DeFi apps, onchain subscriptions, and AI-native transactions. This drives competition, unlike gatekeeper-heavy platforms, unlocking new scenarios for low-dollar trades (e.g., coffee shops saving 15% on $2 transactions).
Adoption and Future Outlook
Stablecoins are surging: 2025 volumes exceed Visa's $13 trillion annually, with B2B at $36 billion. Projections show a $1.6 trillion market cap by 2030. Adoption starts with pain points—remittances, international B2B, and low-margin retail—then scales via network effects.
Tailwinds include cheaper ramps, shared incentives, and infrastructure upgrades making transactions sub-1-cent. As the "read-write-own" internet era dawns, stablecoins will enable user-owned protocols, outpacing closed corporate systems. Businesses are integrating via providers like Openfort for future-proof infrastructure.
Challenges to Consider
Stablecoins aren't without hurdles: evolving consumer protections, irreversible transactions, and a learning curve for institutions. However, the GENIUS Act and MiCA address these with audits, backing requirements, and anti-scam measures. Ecosystem tools like wallet infrastructure and embedded solutions are bridging gaps, ensuring safe, compliant adoption.
Conclusion
Stablecoin payment rails settle in seconds for fractions of a cent, run 24/7, and in 2026 sit inside a regulatory perimeter that's finally legible. For merchants that want acceptance, Stripe's 1.5% checkout is a reasonable answer. For developers building fintechs, neobanks, remittance apps, marketplaces with on-chain balances, or agentic spend, anywhere the wallet IS the product, the assemble-it-yourself path wins. Smart-account wallets, KYC vendor hooks, sanctions screening, and a policy engine you control: that stack absorbs MiCA, GENIUS, the Travel Rule, and whatever comes next without a replatform.
Ready to build on stablecoin payment rails? Start with the Openfort docs or jump straight to pricing. For the regulatory map, see Stablecoin Regulation and Licensing. For the fintech-builder pattern, see How to Build a Fintech with Stablecoins.
Further reading: